MEDIA
FIXED INCOME: BETTER DAYS AHEAD
| After a challenging decade for bonds, higher starting yields may offer a more attractive outlook. We look at what changed, why fixed income still matters and what may lie ahead.
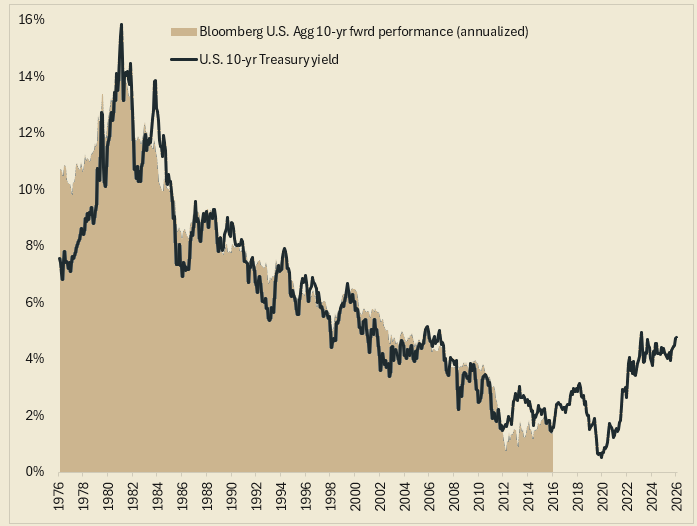
“No matter how dark the night, somehow the sun rises once again and all shadows flee.” — Vern McLellan Bond investors have weathered a long proverbial storm of poor returns. Over the past ten years, bonds, as represented by the Bloomberg U.S. Aggregate Bond Index (the “Agg”), have averaged a paltry 1.3% annual total return. Over the past five years alone, the Agg has declined nearly 3%. Given that fixed income has traditionally been a relatively stable contributor to portfolio performance, this extended period of disappointing returns has prompted several questions in our inbox lately: “What happened?”, “Why even own bonds?”, and “What do we expect going forward?” What happened? Why own bonds? Ultimately, we believe a portfolio’s fixed income allocation should be aligned with the investor’s risk tolerance, liquidity needs, time horizon, and overall financial objectives. What do we expect going forward? After a challenging decade, the setup for bonds looks considerably different than it did just a few years ago. Higher starting yields have restored a more meaningful income component to fixed income and, in our view, make the asset class an important consideration for well-diversified portfolios. Sources: Bloomberg and SEIA. Monthly data: September 30, 1976 – August 31, 2026. |
Read More
Market Commentary|Mar 2026
Market Perspective: Navigating Private Credit Headlines and Interval Fund…
Market Commentary|Nov 2023